

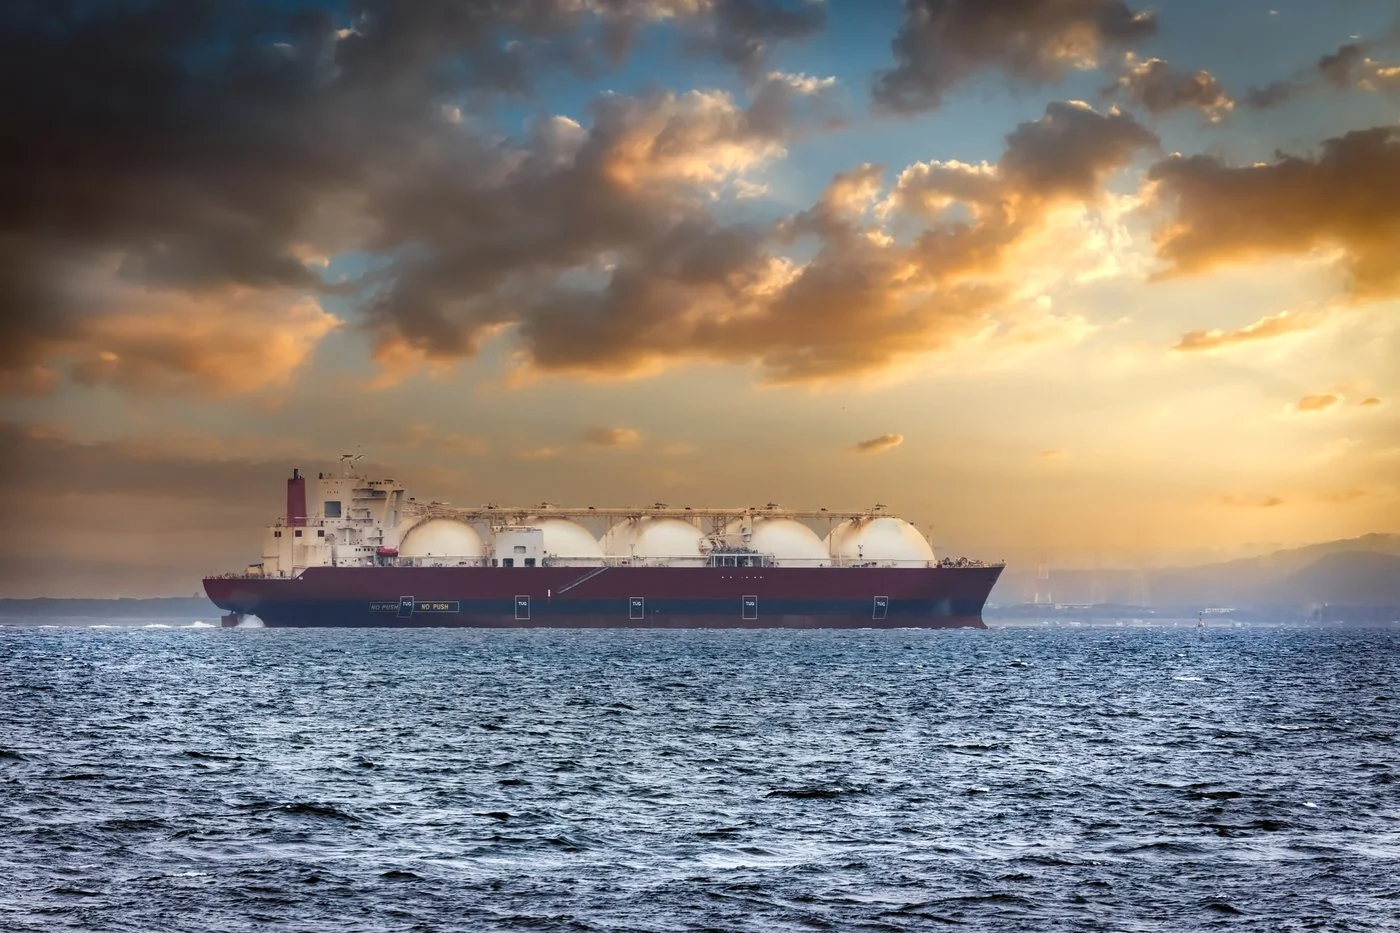
Matt DiLallo of The Motley Fool favors EQT over LNG exporters for its export-market and AI-power exposure. He estimates EQT's five-year deal to supply 0.5 million tons of LNG annually from 2028 should add $45 million to 2028 free cash flow, based on recent gas prices.
EQT has not invested directly in an LNG terminal, but owns midstream infrastructure, including an interest in the Mountain Valley Pipeline, and has signed capacity deals for several export projects. Its latest agreement is with a large Asian energy company and sources gas from Gulf Coast facilities. EQT expects international pricing exposure for 10%–15% of its volumes from 2030 under current contracts.
Unlike LNG terminal operators, which generally lock in much of their volumes through long-term contracts, EQT remains exposed to gas-price swings. The article puts its 2026 cash-flow breakeven around $2 per MMBtu and says hedging part of production can limit upside. DiLallo estimates EQT would generate about $10 billion in cumulative free cash flow through 2030 at $2.75 per MMBtu. EQT also signed a 10-year gas supply deal for a West Virginia power project at a meaningful uplift to local pricing.
