

After a volatile week that left the S&P 500 up 1.2%, investors are watching the September jobs report, Sept. 30 PCE inflation data and movements in interest rates, oil and tech stocks. The consensus forecast calls for 100,000 new jobs and 4.2% unemployment.
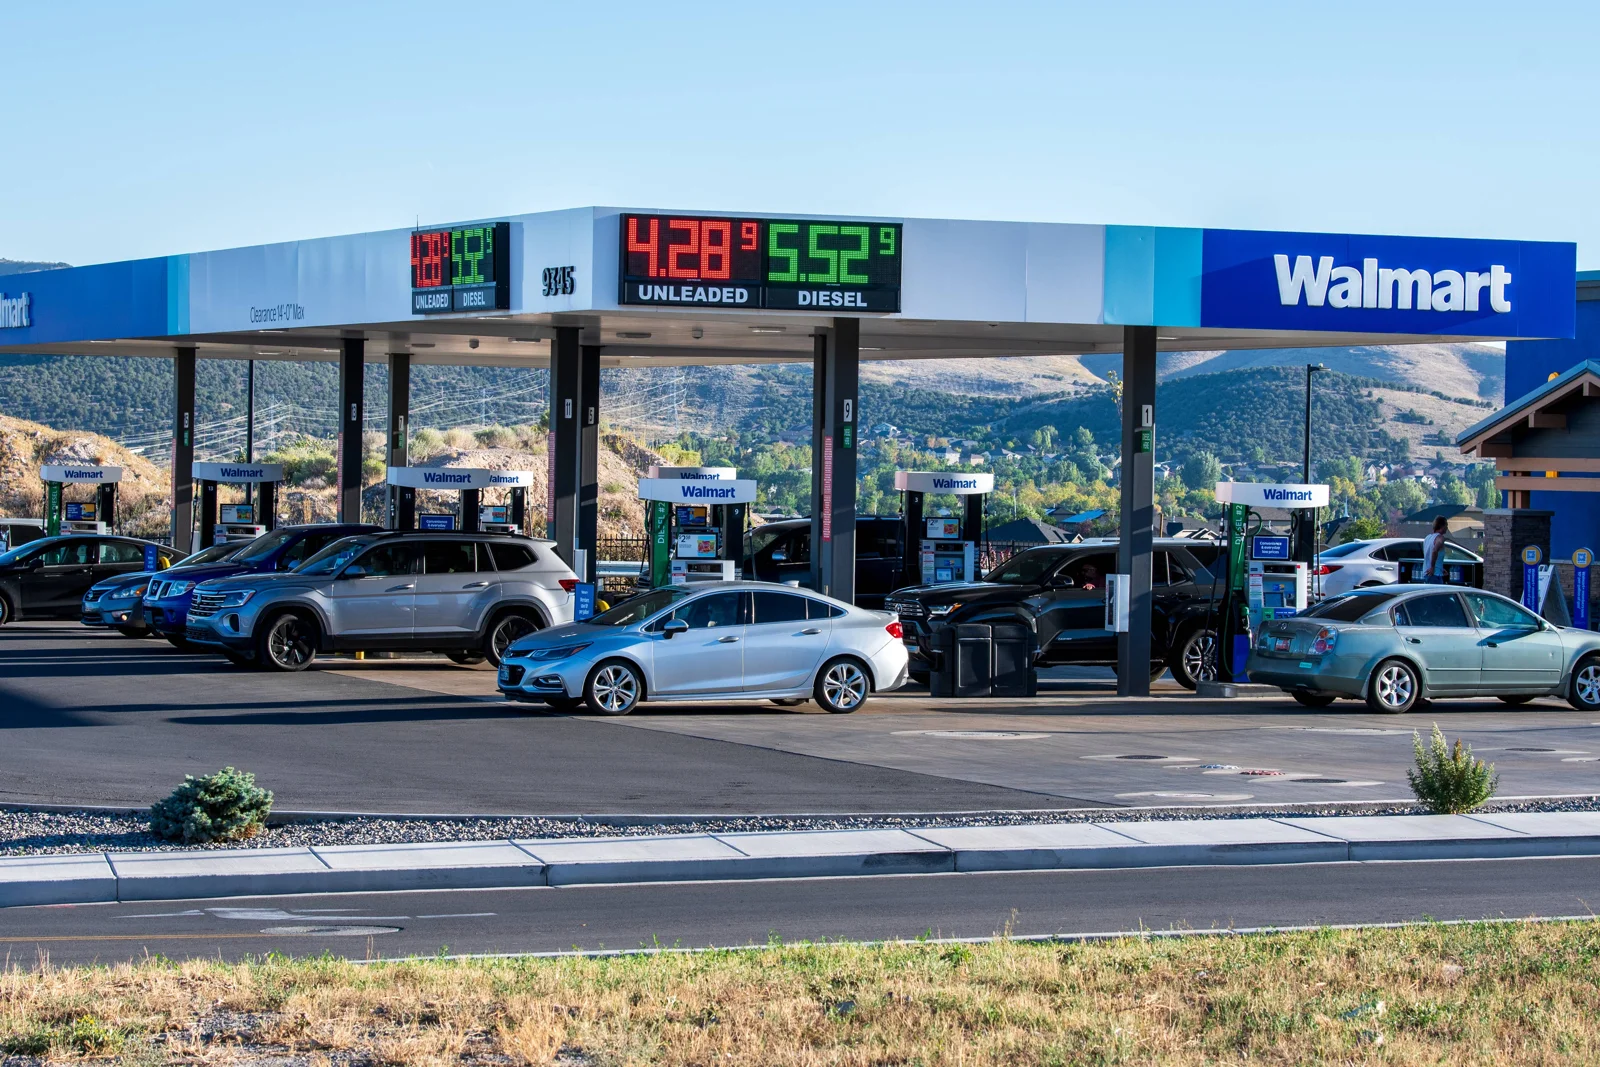
The Dow gained 0.3% and the Nasdaq 2% for the week. The 10-year Treasury yield hit 5.23% on Sept. 25, its highest since July 2006, before closing at 5.17%. August’s 162,000 jobs figure may be revised; unemployment was 4.1%. The Commerce Department’s personal consumption expenditures index, due Sept. 30, could affect whether the Fed raises rates again Oct. 28. Diesel topped $6.50 a gallon nationally and nearly $8.50 in California. Separately, at least 16 trucking companies began bankruptcy proceedings between late August and Sept. 21.
Iran proposed a seven-day ceasefire followed by reopening the Strait of Hormuz and nuclear talks. The Wall Street Journal reported that President Trump rejected the offer and expected to resume bombing after the Nov. 3 midterms. Energy was the S&P 500’s leading sector for most of 2026, up 38.4% year to date; tech led last month. Micron, up 279% year to date, reports after the Sept. 30 close, with consensus estimates of $51.1 billion in revenue and $31.45 a share in earnings. Traders expect the war to end eventually and oil to fall 17%–20% by spring 2027, an uncertain outlook.
